Loading dispatches...
← Return to NewsroomEconomy
How to Build a Better Retirement-Spending Plan Than the 4% Rule
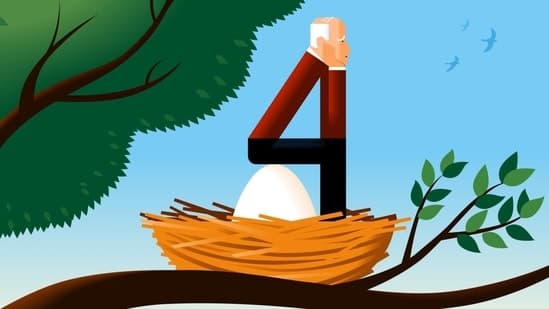
Most retirees are familiar with the 4% rule.The 4% rule has some blind spots. It assumes a 30-year retirement, but some retirees will need their money to last longer than thatIt’s the guide many financial pros have extolled for decades for the decumulation phase of retirement—the time when you finally start tapping the money you’ve spent decades (ideally) saving and investing.Withdraw 4% of your portfolio in the first year of retirement, then adjust that amount for inflation every year thereafter. If your portfolio starts out at $1 million, for instance, you spend $40,000 the first year, then $40,000 plus inflation the next year, and so on.The rule was devised in 1994 by financial adviser William Bengen after research showed that retirees with a balanced stock-and-bond portfolio who followed that math wouldn’t have run out of money over any 30-year period since 1926—even when economic conditions were bad.It’s pretty simple. Maybe too simple.The 4% rule has some blind spots. It assumes a 30-year retirement, but some retirees will need their money to last longer than that. It also assumes the markets will perform as well as they have over the past century. As a result, researchers have been lowering or raising the figure for years. Investment research firm Morningstar revises its estimate annually; it was 3.3% in 2021 and 3.9% this year. Bengen himself has said that a safe number could now be 4.7%.The rule’s deeper problem is its rigidity. Your portfolio amount could double in a market boom during retirement and the rule would still limit you to the same inflation-adjusted amount, which would be unnecessarily frugal. More concerning, your assets could fall by a third and the rule wouldn’t tell you to curtail your spending. You would have to liquidate a bigger portion of your portfolio to withdraw the prescribed amount. If that happens a few years in a row, you run a real risk of eventually outliving your money, despite what the historical data say.The good news is that there are ways to make retirement spending more responsive to how long you’re likely to live and how markets perform. Use the 4% rule as a reference point, rather than have it be the full plan.Your life expectancy mattersInstead of spending a fixed inflation-adjusted dollar amount every year, you need to factor in your life expectancy and the size of your portfolio and then adjust accordingly.You divide your current portfolio balance by the number of years you can expect to live, and spend that much in the coming year. The following year, you do the math again with your new portfolio balance and your new remaining life expectancy. (You can find your life expectancy at your current age in the Social Security Administration’s life tables, which are updated annually. Keep in mind that tables don’t apply to any specific person; they don’t factor in health issues or family medical history. You may want to be conservative and go beyond your life expectancy, or take a chance and reduce it.)If you’re a 70-year-old woman, for instance, your remaining life expectancy is about 16 years. So you would divide your portfolio into sixteenths and spend one of them this year. A year later, you would recalculate using your new balance and your new life expectancy of 15 years, and so on. This allows your spending to rise when your portfolio is up and fall when it’s down.This actuarial approach lessens the chance you’ll run out of money, and it lets good market returns flow through to higher spending.Spending too much—or not enoughBut it introduces a new problem: too much fluctuation in your spending.If markets drop 30% in a bad year, your spending drops by roughly 30%, too. If markets surge in a year when the life tables say your remaining expectancy is five years, the formula tells you to spend a fifth of your portfolio—probably far more than you need or want.The fix is to put guardrails on the actuarial approach, using the 4% rule as your anchor. You set an upper and lower band aro

FANTASTIC BEASTS roam Silicon Valley. Locals are familiar with the unicorn, a startup valued at more than $1bn, the centaur (worth $100m) and the decacorn ($10bn). Lately another creature has been stalking the land: the “zombie” unicorn: a firm once worth $1bn-plus but now a mere shadow of its former self—a prospect to keep venture capitalists (VCs) awake at night.Startups typically aim to spend five to ten years growing before listing on the stock market or finding a buyer. (Unsplash)By May 2026, 332 of the 1,900 unicorns in a database maintained by Ilya Strebulaev of Stanford University had raised money at a valuation at or below their peak (see chart). Of those, 212 were valued at under $1bn. As many as 383 had disclosed no new funding in the previous three years; 41 of these had lost unicorn status. As Mr Strebulaev notes, data on startups are notoriously noisy. Some unicorns may have raised no money because they did not need it. But others may be struggling to justify mythical valuations. It seems that a fair proportion of unicorns have joined the undead.When unicorn-spotting was at its height, plenty of those startups had scant revenues and sketchy business plans. But low interest rates encouraged investors in search of better returns into VC funds. In 2022 VCs raised $223bn, according to Pitchbook, a data provider. Interest rates have since risen and fundraising has fallen, to $66bn last year.Some businesses seem simply to have been wildly overrated. Cameo, a video site where celebrities give personal greetings for a fee, was valued at $1bn in 2021 but is now reckoned to be worth $82m. The value of SonderMind, a platform for finding mental-health professionals, has plummeted from $1.1bn in 2021 to a mere $7m. More broadly, the fundraising downturn has punctured unicorns’ ability to raise more money at their old valuations.Startups typically aim to spend five to ten years growing before listing on the stock market or finding a buyer. Zombies and their backers may find it hard to do either. VC agreements often allow investors to veto public offerings if they believe they would do better to wait. In the past the easiest option has often been to raise more from VCs. But now they are more interested in today’s hot firms than in taking a chance on ageing ones, says Peter Cohan, a tech investor. To convince them, startups often have to accept a cut to their valuation, among other unenviable terms.Nearly half of the firms in Mr Strebulaev’s database valued at less than their peak raised money in 2021. From late next year their investors will start demanding results, reckons Pitchbook. It expects net cuts in valuations of between $500bn and $1trn as firms reprice, scramble to find a buyer or go bust. That is quite a cull: Pitchbook puts the total value of unicorns below the ten most valuable at around $5trn.Falling valuations spell horror for VCs. More recently launched funds have been returning markedly less money to investors than those of earlier vintages, according to the World Economic Forum. They have also underperformed the S&P 500 by a wide mark, particularly those that did not invest in a small club of artificial-intelligence superstars, says Mr Cohan. That will make investors even more reluctant to fund VC firms outside the industry’s top ranks: already, just 5% of them produce 90% of its profits.Spooked VCs are seeking answers. Some have shifted from conventional funds with predetermined lifespans to continuous ones that mix stakes in private companies with liquid holdings in public ones, allowing them to pay investors periodically. Others have turned to the secondary market for shares in private firms, giving investors a way to cash out. But both ideas work best for startups and VCs that are already doing well. They are less suited to rescuing the walking dead.Some VCs hope that if this year’s giga-IPOs of star AI companies are a success, public markets will become more welcoming to tech’s lesser lights. It will sure

Allegations arise that funds from the Annapurna Yojana were misallocated to men, with a case in West Bengal highlighting the issue. A 74-year-old received an unexpected ₹3,000.Annapurna Yojana: Women welfare money deposited into man's account; Trinamool reacts, ‘After filling a 12-page form…’ (PTI Photo)(PTI)Fresh allegations have emerged that money from the Annapurna Yojana welfare scheme was wrongly credited to men. One specific incident in West Bengal has raised serious questions about the state government's distribution system.In this case, a 74-year-old man, Sanjit Biswas, from Chandpur in Nadia district, received an unexpected credit. He visited a local customer service centre on Thursday to withdraw his old-age pension.His account held ₹799. After two months, the ₹2,000 pension was credited, and his balance should have been ₹2,799. Instead, he found ₹5,799 in his account.Centre staff traced the extra ₹3,000 to the BJP government's Annapurna Yojana scheme using his Aadhaar number, according to the Anandabazar Patrika. Biswas said he had not withdrawn the amount.Krishnanagar 1 BDO Ranjan Sardar acknowledged the anomaly, the publication added. He said it might have occurred due to an error. Officials have been sent to Biswas's house for verification, and corrective action is expected.The state began transferring ₹3,000 under the Annapurna Yojana to verified beneficiaries from Wednesday. This incident follows earlier allegations that money from the Lakshmir Bhandar scheme was also deposited into men's accounts, leading to several arrests.All India Trinamool Congress, led by former chief minister Mamata Banerjee, was quick to take a dig at the incident. TMC’s official social media handle shared a screenshot of the news story.“Annapurna Bhandar is also meant for senior citizens, BJP Bengal? After filling a 12-page form, undergoing multiple rounds of verification, and facing endless scrutiny, how did this individual in Nadia end up receiving Annapurna Bhandar benefits?” Banerjee’s party asked.“So much for your claims of ‘strict verification’ and ‘zero loopholes’. SLOW CLAPS!” it added.Social media users reacted to the post.“Further, almost all the so-called below poverty line are essentially earning over 12,00 to 15,000 per month as they are working in nearby flats and houses as house assistants. THIS NEEDS TO BE KEPT UNDER CONSIDERATION,” wrote one of them.“Kya fursat hai (You have a lot of time) - auditing which individual gets what from the govt. SEBI ban gaye aap log - watchdog. Good. Keeps the govt in check. Do do,” commented another user.BJP’s AllegationsThe BJP, now in power, has repeatedly accused the previous TMC government of mismanagement. A 65-year-old homoeopathy doctor from Pingla in West Midnapore allegedly received widow pension money for two years.Amlendubikash Mondal, a resident of Yashrajpur village, was earlier arrested and produced before the Chief Judicial Magistrate's court in Midnapore. The judge ordered three days of police custody.Mondal claimed that he had applied for an old-age pension in 2022. He said he did not know how the widow's pension had started reaching his account.He also alleged that he had informed local panchayat members after noticing the deposits. No action was taken at the time, he claimed.About the AuthorSounak MukhopadhyaySounak Mukhopadhyay covers trending news, sports and entertainment for LiveMint. His reporting focuses on fast-moving stories, box office performance, digital culture and major cricket developments. He combines real-time updates with clear context for everyday readers. Sounak brings newsroom experience across breaking news, explainers and long-form features. He has a strong emphasis on accuracy, verification and responsible storytelling. His work tracks audience behaviour, celebrity influence and the business of sport and cinema. He helps readers understand why a story matters beyond the headline. Sounak has contributed to widely read digi

Discussion (0)